MacroFilters
Robust Trend-Cycle Decomposition for Macroeconomic Time Series
Provides high-performance tools for macroeconomic trend
extraction and filtering, specifically designed to solve the end-point
problem in real-time. Implements the MacroBoost Hybrid (MBH) filter
using penalized P-splines and gradient boosting. Unlike the standard
Hodrick-Prescott filter, 'MacroFilters' utilizes component-wise
L2-boosting with robust loss functions (Huber) to handle extreme
transient shocks (e.g., COVID-19) without inducing spurious trend
shifts. The algorithm includes an automated two-layer diagnostic stage
for unit roots and structural breaks, optimized via corrected AICc for
computational efficiency. Methodology detailed in Kinel (2026)
MacroFilters 


Working Paper Available: The econometric methodology and mathematical proofs underlying this package are distributed via SSRN: Robust Real-Time Macroeconomic Trend Extraction: A Gradient Boosting Approach.
MacroFilters is a unified, high-performance library for extracting trend and cycle components from macroeconomic time series. It combines classical filters (Hodrick-Prescott, Hamilton, Boosted HP) with its flagship algorithm, the MacroBoost Hybrid (MBH) — a gradient-boosting filter with Huber loss that is immune to structural shocks such as COVID-19, financial crises, and wars.
Why MacroFilters instead of mFilter or neverhpfilter?
- Robustness:
mbh_filter()replaces $L_2$ squared-error loss with Huber loss, ensuring extreme exogenous shocks never distort the structural trend. - Speed: The HP implementation uses sparse-matrix Cholesky
factorisation (
Matrix), scaling as O(n) instead of the dense O(n³) used by legacy packages. - Input agnosticism: Pass a plain
numericvector, ats, anxts, or azooobject — the output always matches the input class seamlessly.
The End-Point Problem: Solved
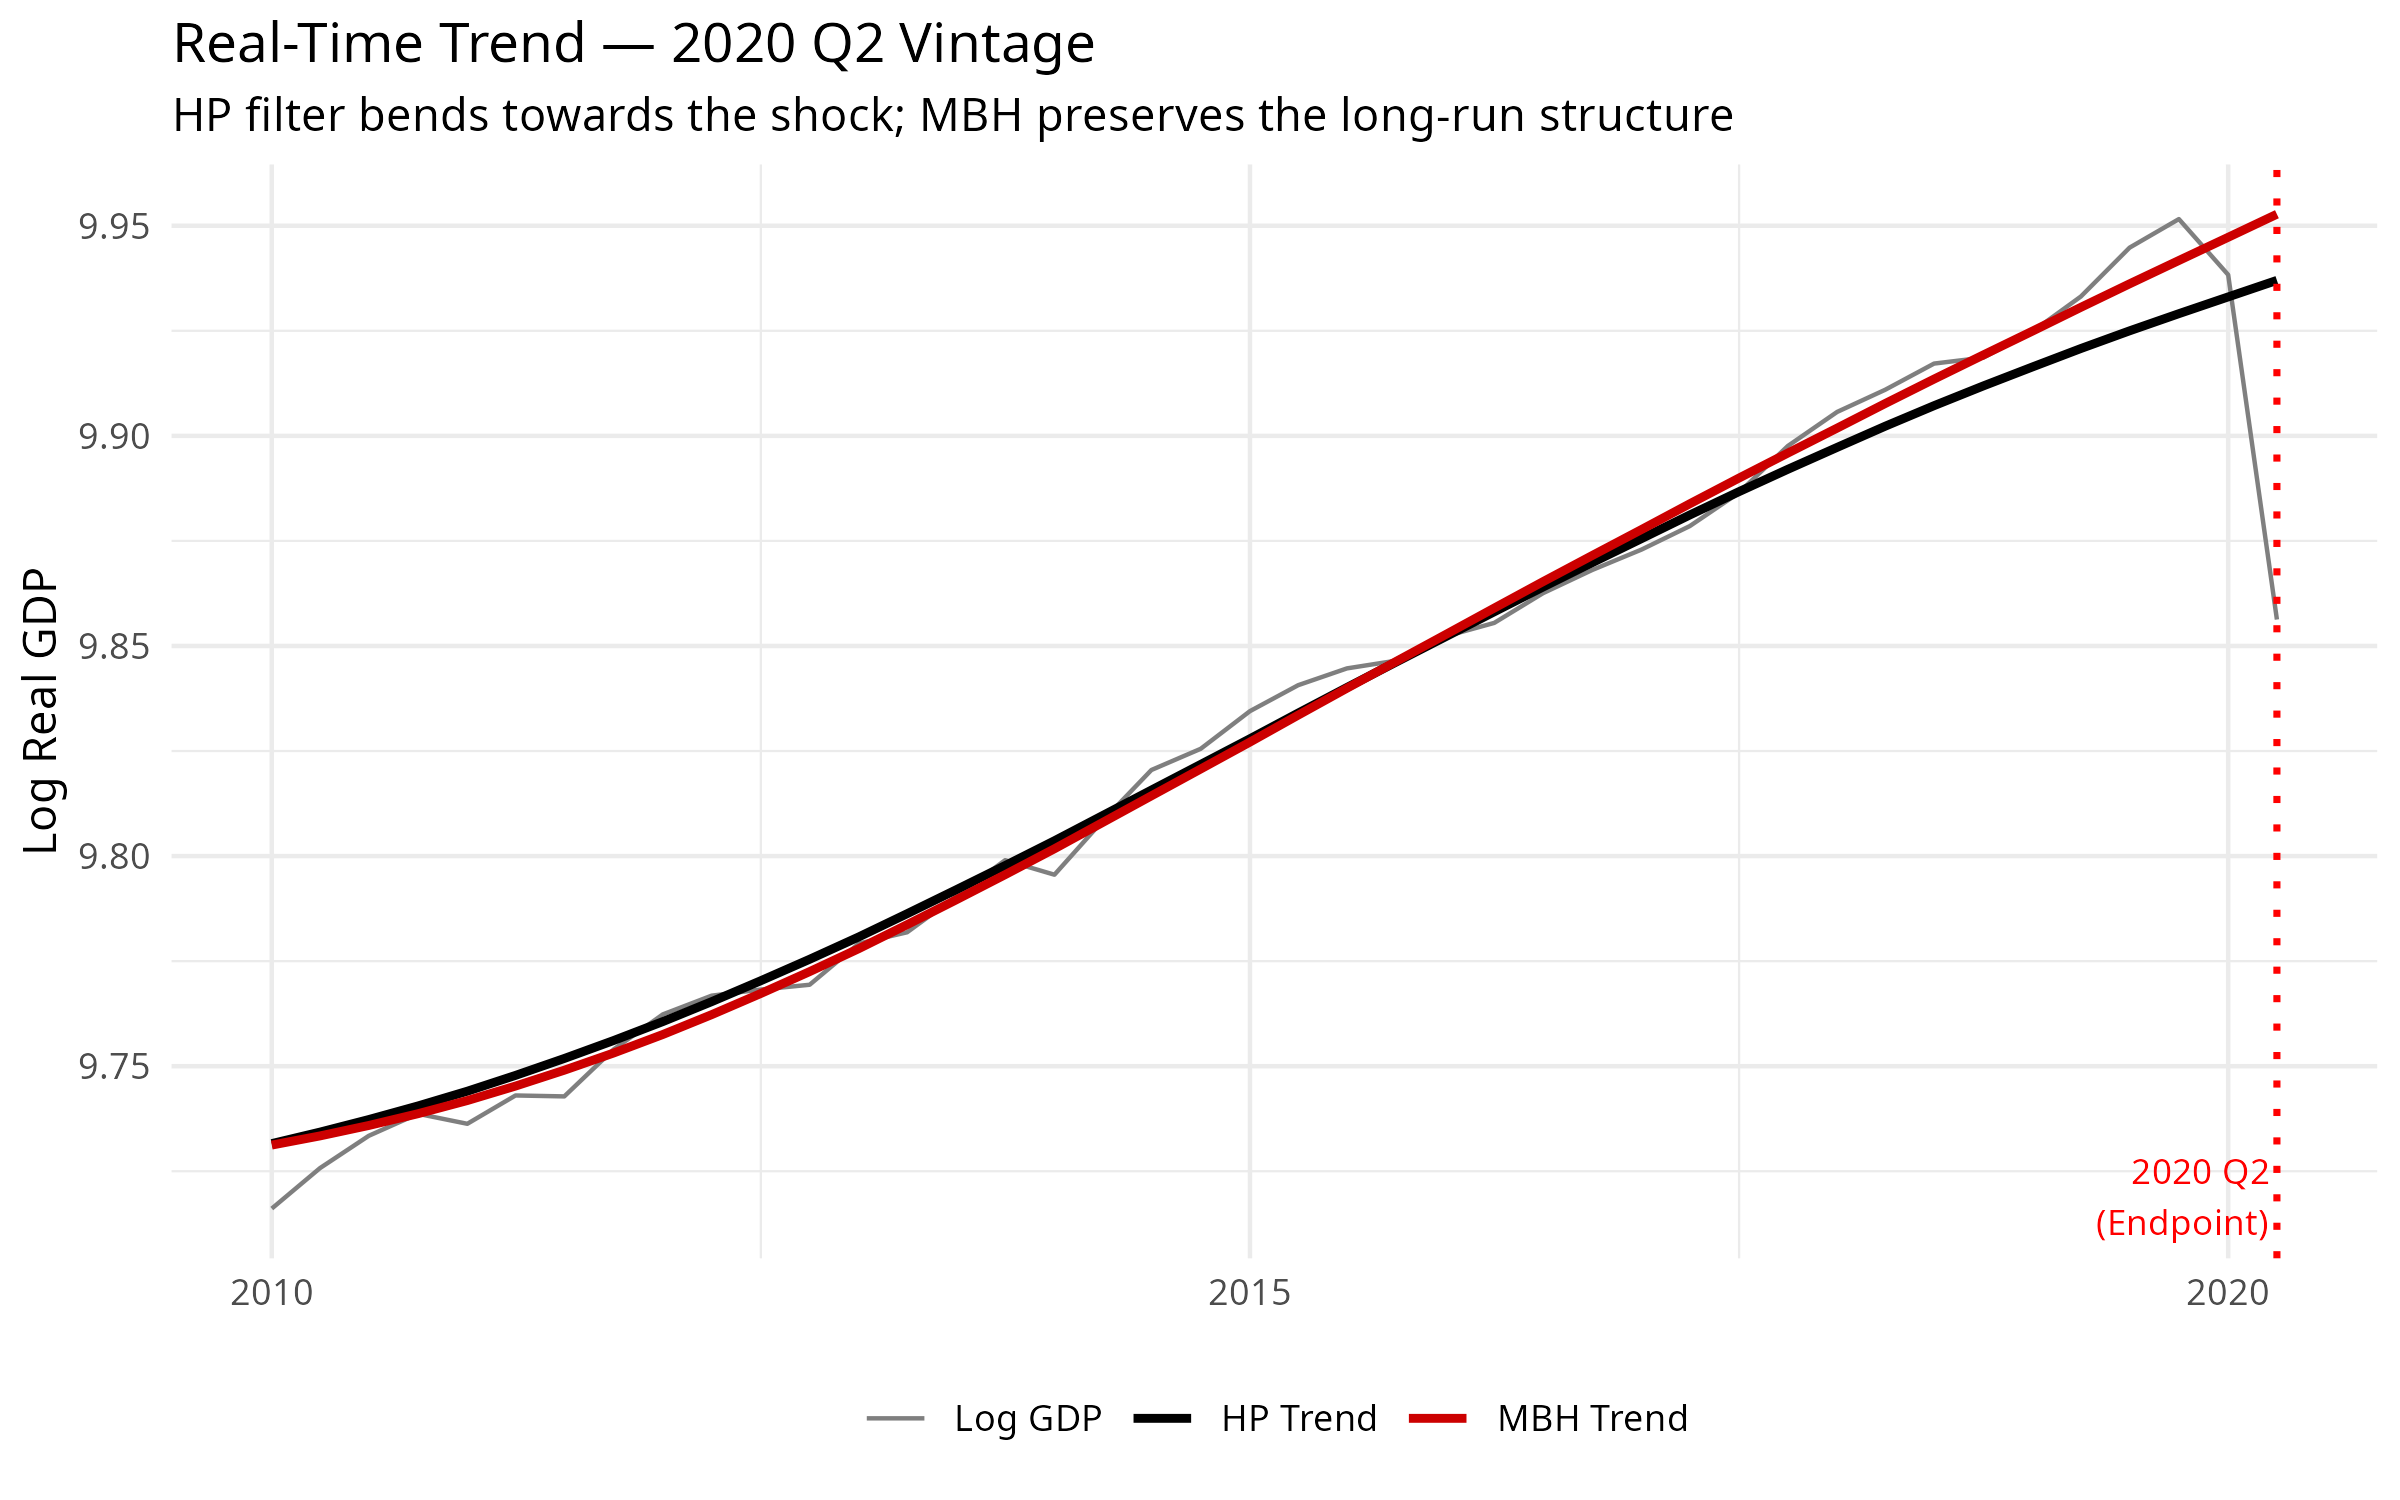
During extreme black swan events, traditional filters anchored in $L_2$ loss mechanically deform the long-run structural trend to absorb massive, transitory outliers.
As demonstrated with Real US GDP during the 2020 Q2 COVID-19 collapse, the standard HP filter bends towards the shock. The MBH filter isolates the exogenous shock entirely within the cyclical component, preserving absolute trend integrity in real-time.
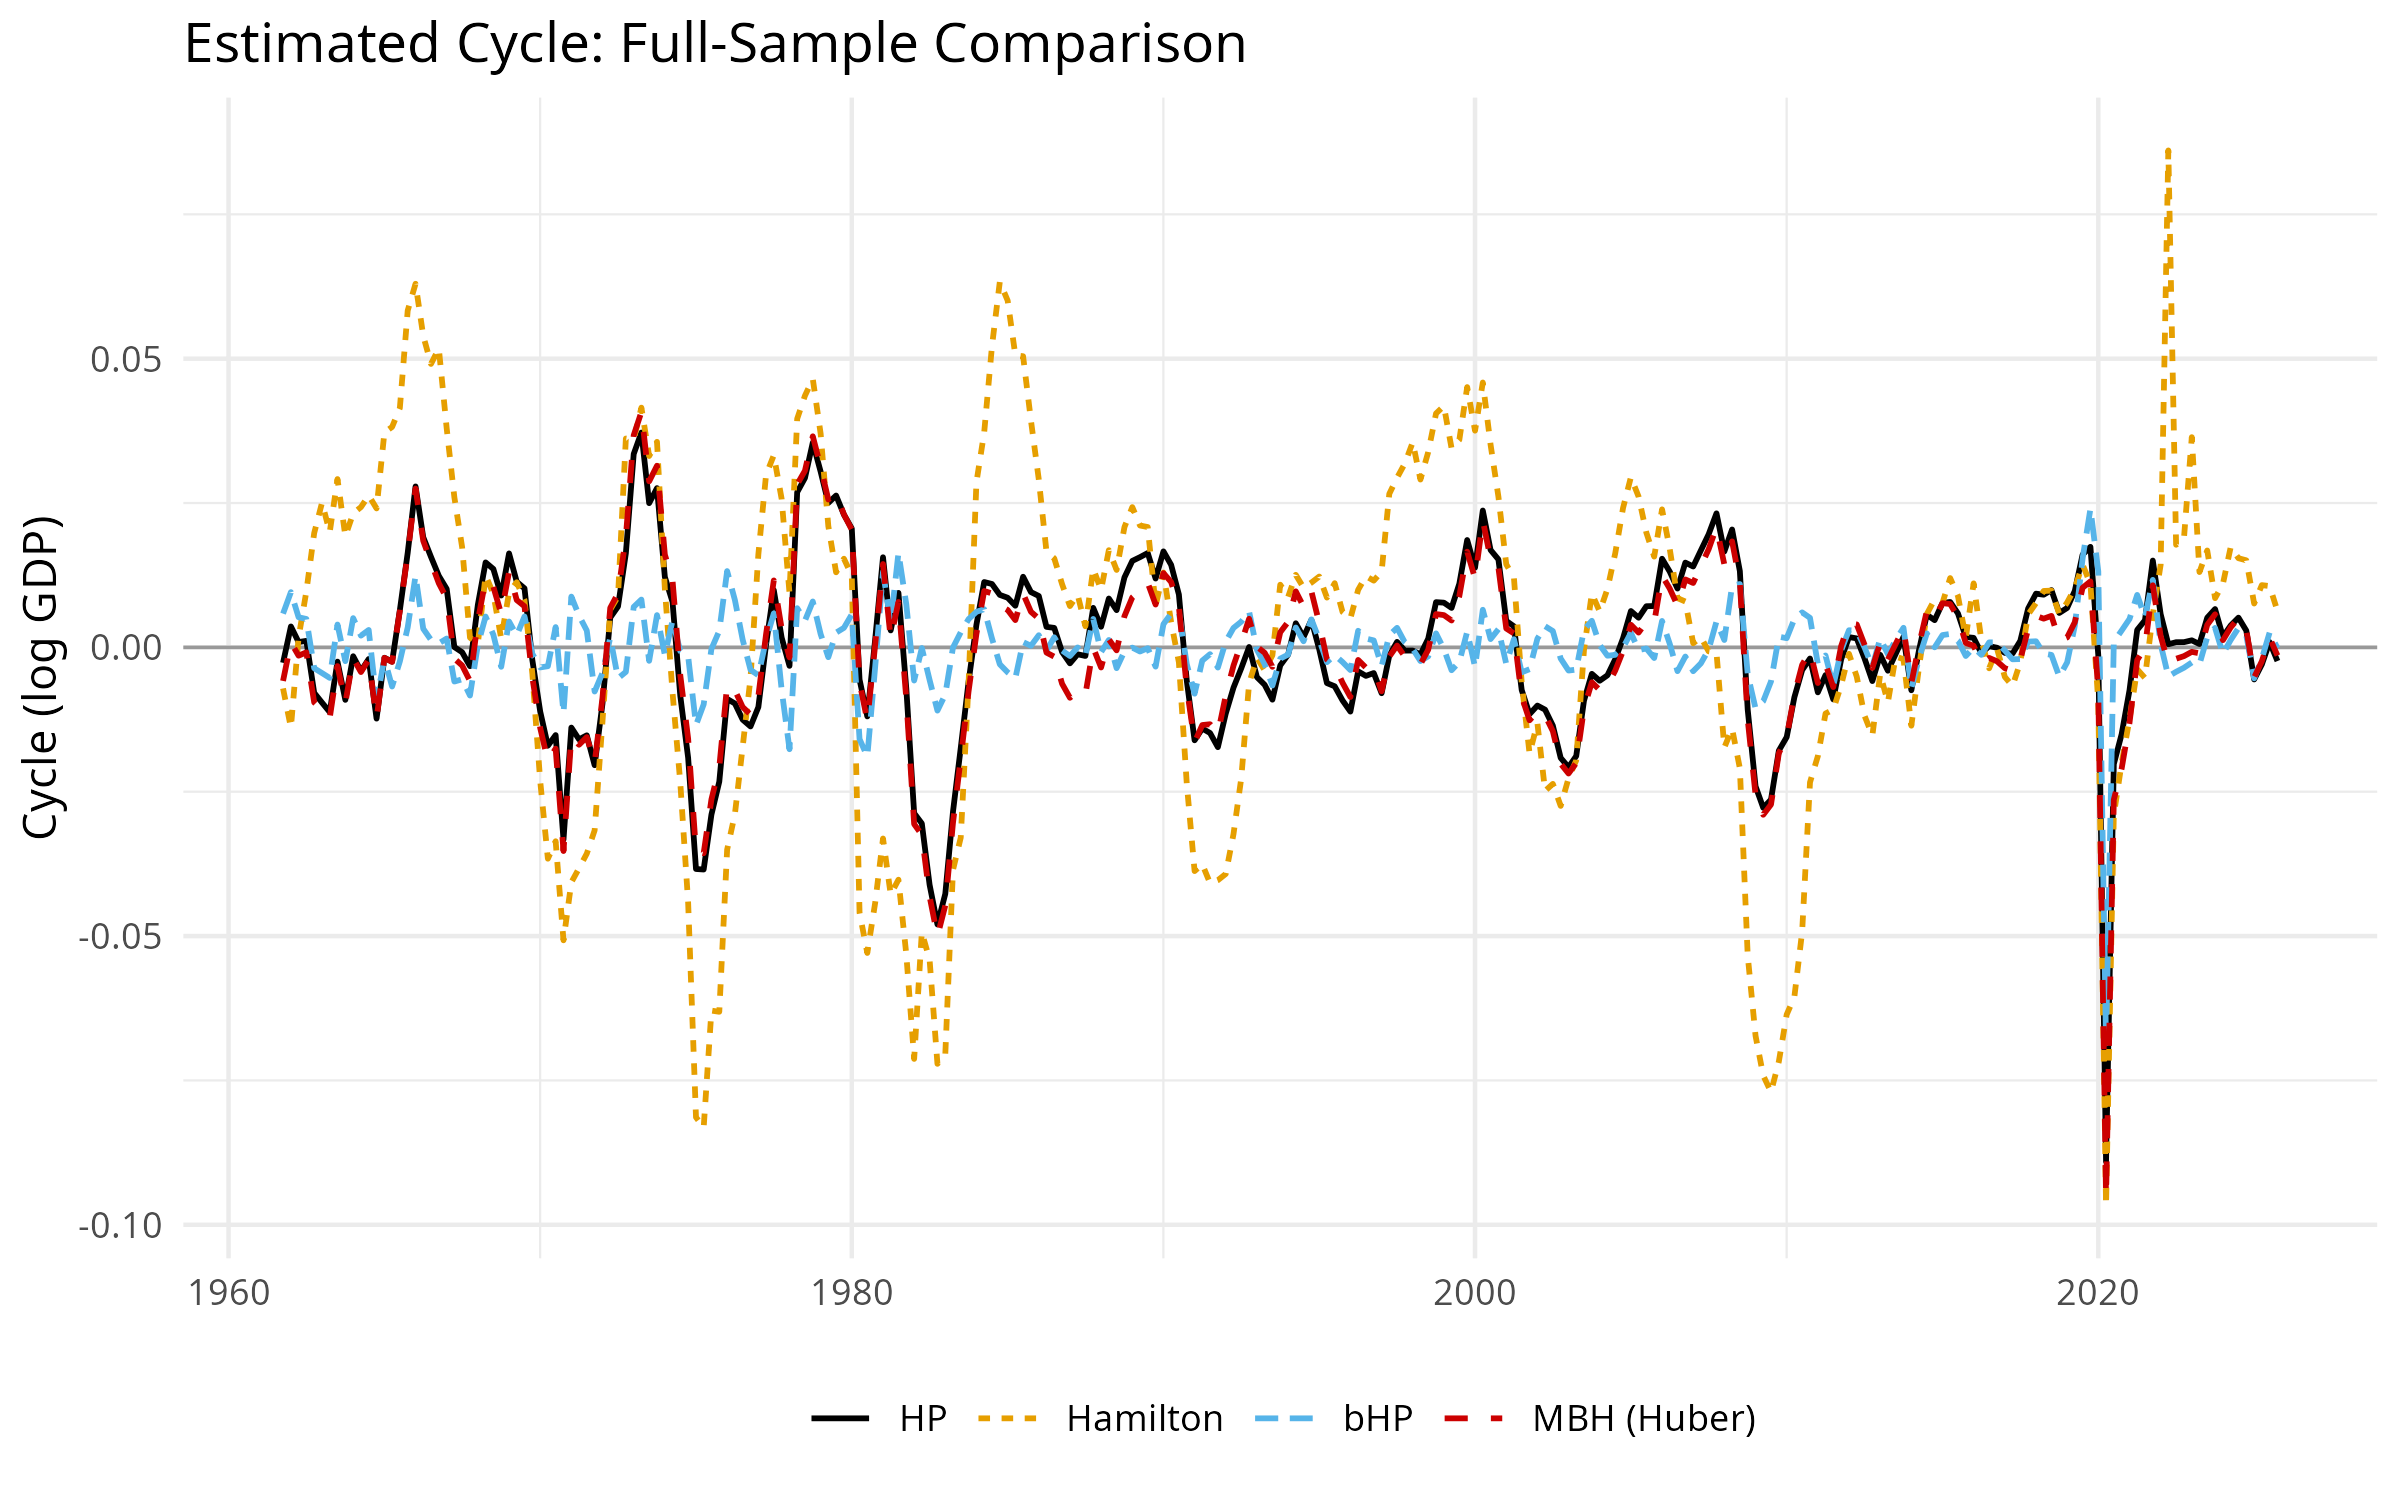
Furthermore, ex-ante spectral alignment ensures the MBH filter perfectly matches the baseline cyclical volatility of the industry-standard HP filter during normal conditions, unlike the excessively volatile Hamilton filter.
(Plots generated using real-time vintage data from the Federal Reserve Economic Data - FRED).
Installation
# install.packages("devtools")
devtools::install_github("michal0091/MacroFilters")
Quick Start Arsenal
| Function | Method | Key Advantage |
|---|---|---|
hp_filter() |
Hodrick-Prescott (1997) | Sparse O(n) implementation |
hamilton_filter() |
Hamilton (2018) | OLS regression, no spurious cycles |
bhp_filter() |
Boosted HP — Phillips & Shi (2021) | Iterative fitting with BIC/ADF stopping |
mbh_filter() |
MacroBoost Hybrid | Robust to outliers via Huber loss |
All functions return a list of class c("macrofilter", "list").
library(MacroFilters)

# Fast, agnostic filtering on any time-series object
hp_result  <- hp_filter(us_gdp_xts)
mbh_result <- mbh_filter(us_gdp_xts)

# Access components directly
mbh_result$trend
mbh_result$cycle

# Add 95% bootstrap confidence bands and plot them
mbh_ci <- mbh_filter(us_gdp_xts, boot_iter = 50L)
autoplot(mbh_ci)            # ggplot: trend, observed series and confidence ribbon
Further Reading
vignette("introduction", package = "MacroFilters")— full walkthrough of all four filters and the S3 print/meta interface.vignette("uncertainty_bands", package = "MacroFilters")— confidence bands via block bootstrap and theautoplot()method.